How Much Compensation For A Car Accident in Utah?
/in Blog/by Chris CockayneSeriously, you were hurt, your medical bills, the work you have missed, how the crash has affected your daily life, who was at fault, and how much insurance is available to pay. Two crashes that look alike on paper can end up with very different results.
Table of Contents
ToggleUtah is also a no-fault state, which changes how these claims work. Your own personal injury protection (PIP) coverage pays certain medical costs first, and you can go after the at-fault driver for more only once your injuries meet specific requirements.
Below, we cover what you can claim, how fault and insurance limits can change what you receive, and what evidence helps show the full extent of your losses.
What Determines How Much Compensation You Can Get?
Most of what you can claim falls into two buckets. The first is money you can point to: hospital bills, physical therapy, prescriptions, and the paychecks you missed.
Hold on to every bill and write down how you feel from day to day. Utah is a no-fault state, so your own insurer will handle the first $3000 of medical bills through PIP, no matter who caused the crash.
Once your injuries cross a certain line, you can go after the other driver for more, including pain and suffering. That line is usually more than $3000 in medical expenses or for an injury like a broken bone, permanent damage, or disfigurement.
Fault changes the number too. If you are partly responsible, your payout shrinks by that percentage. At 50% or more, you get nothing.
Then there is another driver’s policy. Utah’s minimum is $30,000 per person and $65,000 cash per accident for injuries, and plenty of drivers carry exactly that. A serious injury can use it up fast.
If your losses go past their policy, your own underinsured motorist (UIM) coverage may help cover the difference. Most injury lawsuits have to be filed within four years. Claims against a city or the state have much tighter deadlines, so ask early.
What Types of Compensation Can You Recover After a Utah Car Accident?
Car accidents in Utah can involve various kinds of injuries, and not every claim has all of them. Your compensation completely depends on how badly you were hurt and how clear it is who caused the crash.
Medical Expenses
One of the easiest parts to prove is medical bills, so they usually anchor the claim. That means the ambulance, the ER, the scans, surgery, therapy, and the pharmacy receipts. Where people get stuck is with future treatment.
If you might need another surgery or a year of therapy, get your doctor to say so in writing and put a cost on it. An adjuster will brush aside, “I think I’ll need it.”
Lost Wages and Earning Capacity
If you missed work, you can claim the pay you lost, and that includes sick days and PTO you burned through. It gets harder when you go back and can’t do the job the way you used to.
A roofer who can’t climb or a nurse who can’t lift patients has lost a lot more than a couple of paychecks. This is lost earning capacity, and you’ll want your pay history and a doctor’s work restrictions to back it up.
Pain and Suffering
These are called non-economic damages. They cover the pain itself and also the stuff that’s hard to measure. For example, the stress, the nights you can’t sleep, and the weekends you have given up.
There is no cap on them in car accident cases, but you can only claim them from the other driver if you meet the threshold above. Insurers fight this one the hardest because there is no invoice. If you can write a few lines every day.
Six months from now, you want to remember what week three felt like.
Vehicle Damage
Your car counts too. Repair it if it can be fixed. Its market value just before the crash if it’s totaled, plus towing, storage, and the rental. People forget about diminished value.
A repaired car with a collision on its history is worthless when you sell it, and you can ask the other driver’s insurer to cover that gap.
Punitive Damages and Wrongful Death
Punitive damages are rare. They are meant to punish, not repay, and they are saved for conduct well past carelessness, like driving drunk. Utah has its own rules for when they can be awarded.
If someone is killed in a crash, the family can bring a wrongful death claim for funeral and medical bills, the income and support that person would have provided, and the loss of their companionship.
What Utah Settlements Look Like: Ranges, Data, and a Simple Estimate
No two cases are the same, but public sources give helpful guardrails. The average payout for minor injuries in Utah ranges from about $6,700 to over $400,000, with a moderate claim near $33,000.
Minor claims range between $10,000 and $25,000, while severe claims are between $50,000 and $75,000 or more, according to another Utah source. Depending on the proof, the care, and the coverage, these figures will differ.
A fair estimate starts with your numbers, not a generic online tool. List your economic losses to date, then add reasonable future care if doctors expect more treatment. Non-economic losses can be estimated with a multiplier approach that adjusts for the length of recovery, lasting pain, and limits on daily life.
A short sprain with quick recovery might use a low multiplier. A broken bone with months of therapy and sleep problems may justify a higher one. Always adjust for fault and policy limits.
Quick, Centered Checklist For Your Estimate
- Add medical bills and related costs
- Add lost wages and job impact
- Add future medical care if expected
- Apply a fair pain-and-suffering factor
- Reduce by your percent of fault
- Check the other driver’s policy limits
How Insurance Companies Calculate Car Accident Settlements
Insurance companies do not simply add your medical bills and send a check. Adjusters review multiple factors before determining settlement value. These factors often include:
- Medical expenses
- Future treatment costs
- Lost wages
- Reduced earning capacity
- Pain and suffering
- Permanent disability
- Comparative fault
- Available insurance coverage
- Strength of evidence
The more documentation supporting your injuries and losses, the stronger your position during settlement negotiations. The risk of litigation remains in the insurer’s mind. If they believe a jury could award more than their offer, they may increase settlement discussions to avoid litigation.
How Insurance Companies Evaluate Car Accident Claims
An adjuster works for the insurance company, and part of the job is testing your claim. A gap in treatment, a late first doctor’s visit, or any way to put part of the blame on you gives them room to lower the number.
In Utah, if they get you to 50% at fault, your claim is gone. They also look at what the at-fault driver’s policy can actually pay. If your losses are well past the limit, that limit becomes the real conversation.
Be careful with the first offer. It often shows up before anyone knows if you’ll need more treatment, and once you sign a release, you can’t go up for more.
Realistic Settlement Examples You Can Learn From
Here are some hypothetical examples, just to explain to you how the things fit.
Example #1: Neck Strain
Two days off work, $2,200 in medical bills. PIP pays the bills. With no fracture, no lasting injury, and bills under $3,000, this driver generally can’t claim pain and suffering from the other driver. Lost income beyond what PIP pays may still be recoverable.
Example #2: Broken Wrist
Broken wrist. $8,500 in medical bills and $3,000 in lost pay. A fracture opens the door to pain and suffering, but nothing in Utah law turns it into a set number. If this driver were 20 percent at fault, everything gets cut by 20 percent.
Example #3: Fractures & Surgery
In the case of fractures and surgery, suppose the bills are up to $68,000. $14,000 in lost pay and $20,000 in future care. If the other driver only carries the $30,000 minimum, that runs out fast, and the injured driver’s own underinsured coverage, if they have it, may help with the rest.
How Fault and Insurance Limits Affect Your Compensation
Fault: Utah reduces your payout by your share of the blame. If your damages are $100,000 and you are 30 percent at fault, you collect $70,000. Insurers know this, which is why they push to shift even a little blame onto you.
Insurance Limits: Utah minimum coverage is $30,000 per person and $65,000 per crash for injuries, and plenty of drivers carry only that.
If your losses are higher, the policy is usually the ceiling, no matter what a jury might think your claim is worth. Your own underinsured motorist coverage, if you have it, may cover part of the rest.
Mistakes That Can Reduce Your Compensation
A strong claim can still lose value over small things. Watch out for these.
- Putting off the doctors. A sore neck you ignore for a week hands the insurer a gap to point at. Quitting therapy early because you feel a bit better does the same.
- Giving a recorded statement. The driver’s adjuster will call fast and sound friendly. You don’t have to give one; a casual “I’m okay” can come back to you.
- Posting on social media. One photo from a cousin’s wedding can end up in front of the adjuster.
- Taking the first offer. It often comes before you know what treatment you’ll need, and a signed release is usually final.
Can Vehicle Damage Affect Compensation?
Yes. Compensation is not limited to medical bills and lost wages. However, you may get money for the lost value of your car after the accident, even after repairs. It includes:
- Repair costs for your vehicle
- Towing and storage fees
- Rental car expenses/repair estimates
- Loss of your car’s value after the crash
Sometimes a repaired car is worth less than before. This is called diminished value. Buyers may pay less because the car now has an accident record.
To support your claim, keep the following:
- Vehicle damage photos
- Repair bills
- Vehicle value reports
What If the At-Fault Driver Has No Insurance or Not Enough?
Plenty of Utah drivers carry only the minimum, and some carry nothing at all. If the driver who hit you has no insurance or drove off and was never found, your own uninsured motorist (UM) coverage may pay for your losses, up to your policy limit.
If they do have a policy but it’s too small, underinsured motorist (UIM) coverage may pay the difference above what they carry. Both depend on the terms of your own policy, so check what you have.
The state minimum for bodily injury is $30,000 per person, and one surgery can use that up. Look at who else was involved, too. If the driver was on the job, their employer might be responsible.
If the car belonged to someone else, the owner might be. And if a city or a state ignored a dangerous road, that’s a separate claim with a much shorter deadline, so don’t sit on it.
Hire the Skilled Car Accident Attorney in Utah — Forget Your Worries
A proven personal injury lawyer’s team can collect records, talk to the insurer, and line up the steps that push value higher. If you want a local plan, speaking with a car accident Utah lawyer gives you clear next moves based on Utah law, not guesswork.
Ask how they handle PIP, fault fights, and low policy limits. Ask who will answer your texts and how often they check in. If you feel heard and you get straight talk on fees and timelines, you are in the right place. Many people say they wish they had called sooner. You do not need to carry this alone.
About Chris Cockayne and Cockayne Law
Chris Cockayne has built a practice that keeps clients first. At Cockayne Law, the team focuses on communication, strong case building, and honest advice about value. They gather medical proof early, check policy limits, and watch every deadline so your case stays on track.
If the insurer questions fault, they lean on evidence from photos, scene maps, and witness notes. If a case needs more support, they work with doctors who can explain future care and long-term limits in plain terms.
When talks stall, they are ready to file and keep pushing. If you search for a car accident attorney in Utah, you want someone who knows the local courts and has a calm plan for each stage. Chris and his team fit that mold. If you are not sure where to start, a short call with a car accident Utah lawyer at Cockayne Law can help you decide what to do next.
Rules That Can Raise or Reduce Your Personal Injury Claim
Utah’s no-fault rule means your PIP pays first. Once medical costs reach $3,000 or you have certain serious injuries, you can seek pain and suffering from the at-fault driver. Keep in mind that PIP has limits on wage and service benefits too.
Your case can also be limited by insurance. Utah’s new minimum liability limits as of January 1, 2025, are $30,000 per person, $65,000 per accident for injuries, and $25,000 for property damage. If the at-fault driver has only minimums and your losses are higher, you may need to use underinsured motorist coverage
Finally, the filing deadline matters. It is usually necessary to file a Utah injury lawsuit within four years after a crash. Wrongful death claims have shorter limits. Ask about your deadline early so you do not risk your rights.
A Smart Way to Estimate Value Without a “Calculator”
Online calculators skip key facts and can mislead you. Use this Utah-friendly method instead.
Step 1: Add Economic Losses
Include medical bills, therapy, prescriptions, travel to care, lost wages, and any expected future care from your doctor.
Step 2: Estimate Non-Economic Losses
Use a reasonable factor based on your proof. Short recovery and low pain might justify a small factor. Longer recovery, surgery, or lasting limits may support a higher factor.
Step 3: Adjust for Fault
Your share of fault should be deducted from the total. Unless you are more than 50% at fault, Utah law bars your recovery.
Step 4: Check Insurance Limits
Make sure the at-fault policy can cover the number. If not, look at underinsured motorist coverage on your policy. Utah’s updated minimums can affect this step.
Step 5: Sense-Check with Utah Data
Compare your result to public ranges from Utah cases to see if it feels realistic before talking with the adjuster.
Final Thoughts
Money cannot undo a crash, but a fair result helps you move forward. In Utah, value depends on clean records, solid medical proof, and a plan that accounts for PIP, fault, and policy limits. If you feel stuck or worried about saying the wrong thing to the adjuster, speak with a car accident Utah lawyer who can protect your claim.
If you want local help, Cockayne Law can explain your best next steps in plain language. Stay organized, follow your doctor’s advice, and do not wait on key deadlines. With a steady approach, you can reach a result that matches your losses and lets you focus on healing.
FAQ - Frequently Asked Questions
What is the average payout for a car accident in Utah?
There is no one number. Public sources show wide ranges based on injury level and proof. Minor injury cases can settle in the low five figures, while severe injury cases can reach six figures. Your records, fault share, and insurance limits control the result.
How does Utah’s no-fault PIP change my settlement?
Your own PIP pays the first $3,000 in medical bills per person. Once you reach $3,000 or meet the serious injury triggers, you can seek pain and suffering from the at-fault driver. Keep bills and visit notes to show how and when you passed the threshold.
How much should I expect from a car accident settlement?
Start with your medical bills, lost wages, and likely future care. Add fair pain and suffering based on recovery time and lasting limits. Then adjust for fault and insurance limits. This grounded method beats a generic calculator and fits Utah rules.
How long does a Utah car accident settlement take?
Settlement timelines vary. A simple car accident settlement case can close in a few months. However, disputed or serious injury claims can run a year or more. The timeline largely relies on when your medical treatment stabilizes and how quickly both sides reach an agreement.
What proof helps most with non-economic damages?
Consistent medical notes, a short pain journal, photos of bruising or devices, and statements from family or co-workers about daily limits help a lot. This proof shows the adjuster how the injury changed your life and supports a fair number.
Is it a good idea to contact the other insurance company?
Share basic facts to open the claim, then be careful. Do not guess about pain or fault on a recorded call. Many people choose to let their lawyer handle talks so there are no mixed messages that could harm the case value.
What should I do if I have been in a Utah car accident?
If your medical bills are rising, you missed work, fault is disputed, or the other driver has low limits, call soon. A car accident Utah lawyer can protect your timeline, collect proof, and handle talks while you focus on recovery.
Can I still recover if I was partly at fault?
Yes, as long as you’re less than 50 percent to blame. Your payout gets cut by your share, so if you’re 20 percent at fault, you collect 80 percent of your damages. At 50 percent or more, you generally collect nothing.
How long do I have to file a car accident lawsuit in Utah?
Usually four years from the crash, but not always. Claims against a city or the state have much shorter notice deadlines, sometimes only months. Your own insurance policy can set its own deadlines too. Don’t wait to find out which ones apply to you.
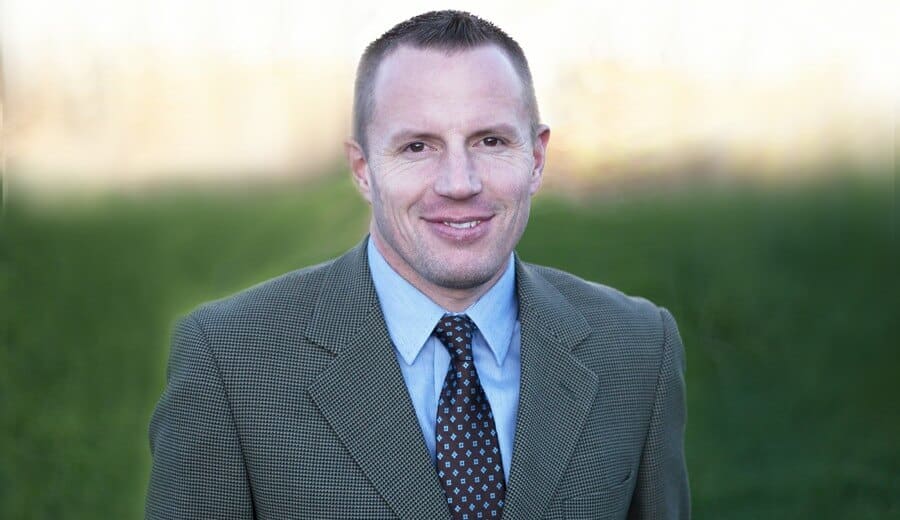
Chris Cockayne is a Utah-based personal injury attorney and the founder of Cockayne Law. Chris focuses exclusively on representing victims of car accidents, dog bites, and other injury claims, helping clients recover compensation for medical bills, lost wages, and long-term care. With over 15 years of legal experience, Chris has handled a wide range of personal injury and motor vehicle accident cases and is known for his client-focused advocacy and strong negotiation with insurance companies. Know more about Chris Cockayne or my other social profiles like Avvo | Martindale | lawyers | Findlaw | Yelp | lexinter | Linkedin | Facebook | and X
This post is also available in: Spanish