When an At-Fault Driver Changed His Story
Case Preview
| Client | Jessica M. |
| Age | 42 |
| Occupation | Elementary school teacher |
| Location | Salt Lake City, Utah |
| Accident date | April 22, 2026 |
| Injuries | Neck strain, mild concussion, lower-back pain |
| Initial insurance position/offer | $12,500 |
| Final settlement | $52,500 |
| Settlement date | September 3, 2026 |
Jessica M. is a 42-year-old elementary school teacher at Backman Elementary School, 601 North and 1500 West in Salt Lake City. My client thought her drive home from work would be just another routine trip. But unfortunately, it wasn’t.
On April 22, 2026, she stopped at an intersection when another driver struck her car from behind. The other driver stepped down and admitted that the crash was his fault at the scene.
My client Jessica exchanged information with the other driver, took a few photos, and initially believed the insurance process would be straightforward. But her guess was wrong.
She’d been diagnosed with a neck strain and a mild concussion that night at Intermountain Health LDS Hospital. As a result, Jessica had to miss work for her follow-up appointments.
And as if that’s not enough, a few days later, the at-fault driver’s insurance company began telling a different story. The insurer questioned how the accident happened and suggested that my client Jessica also contributed to the collision and offered Jessica $12,500 to resolve the claim.
Consequently, she got frustrated and didn’t know what to do next. Like many people in this situation, she turned to Google and searched for a Utah car accident attorney. That’s how she found Cockayne Law and reached out to our team.
When the Insurance Company’s Story Changed
At first, Jessica’s injuries seemed manageable to her. But her neck and back pain continued to worsen in the following days. She eventually needed physical therapy, and her missed time from work increased her lost wages compensation in her claim.
When we reviewed her situation at Cockayne Law’s office, we explained to her that admitting fault at the scene and denying it later is one of the most common excuses drivers make after causing a collision. So she doesn’t need to worry because fault will become clear over time as her case progresses in court on the basis of evidence.
Jessica’s treatment continued for approximately five months; we advised her to keep her medical bills saved. We also documented about $5,600 in her lost income. Her vehicle also sustained approximately $7,800 in damage.
These additional documented facts changed the maths and scope of her personal injury claim. So, we built her case around evidence rather than relying only on what the other driver initially said.
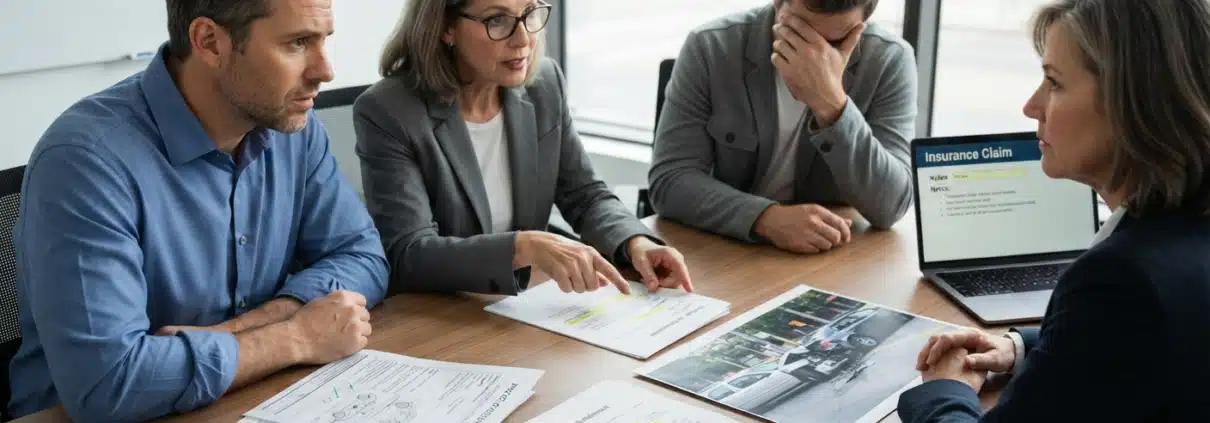
My team collected the available accident documentation, photographs, witness information, vehicle damage records, and Jessica’s medical records. We also looked closely at how the vehicles were damaged and how our collected evidence matched with what happened.
We also noticed that Jessica’s medical expenses had passed the PIP threshold. Therefore, we prepared to file a personal injury claim against the at-fault driver’s insurance.
However, the insurer still did not agree to our position, so we presented the evidence supporting our claim. We showed them Jessica’s medical records and other financial losses (vehicle repair costs and lost wages) and negotiated on her behalf with insurance adjusters.
And when they realized we were also ready to file a lawsuit in Utah court, they agreed to a table talk. And after negotiations, the claim was resolved for an illustrative settlement of $52,500 on September 3, 2026.
The bottom line from Jessica’s case is that what happens after a crash matters just as much as what happens at the scene. An insurance company may change its position later, question the victim’s liability, or minimize injuries.
That’s why preserving evidence, documenting medical treatment, and understanding Utah’s insurance rules make a significant difference when you are pursuing a car accident claim.